Estate planning can sound like something reserved for wealthy families, business owners, or people much older than you.
It is not.
If you have a spouse or partner, children, a home, savings, investments, life insurance, or even a car and a bank account, you already have reasons to think about your estate plan. You do not need millions of dollars to benefit from greater clarity.
Estate planning is simply deciding what should happen to your assets and who should make important decisions if you cannot make them yourself.
For Edmonton families and households across Alberta, that may include preparing a will, choosing decision-makers, reviewing life insurance, updating beneficiaries, and organizing important financial information.
Let’s walk through five practical steps you can take this year.
What Does Estate Planning Mean in Plain English?
In plain English, estate planning is preparing instructions for your family and the professionals who may need to help them.
Your plan may answer questions such as:
• Who should receive your assets?
• Who would care for your children if you died?
• Who could manage your finances if you became unable to do so?
• Who would make personal or health-care decisions for you?
• Where are your accounts, insurance policies, property records, and important documents?
• Will your life insurance and registered account beneficiaries match your wishes?
A complete estate plan often includes three core Alberta documents:
| Document | What it generally does |
| Will | Explains how assets in your estate should be distributed after your death |
| Enduring Power of Attorney | Names someone to manage financial and property matters if you lose capacity |
| Personal Directive | Names someone to make personal and health-care decisions if you cannot make them |
Your will generally applies after death. An enduring power of attorney and personal directive are designed to help while you are alive but unable to make decisions.
You can learn more about Alberta’s official guidance on wills, enduring powers of attorney, and personal directives.
Now let’s turn that information into action.
Step 1: Start With Your Family’s Priorities
Before you think about forms, lawyers, or financial products, think about the people and priorities your plan is meant to protect.
Ask yourself:
• Who depends on my income?
• What would my family need if I were no longer here?
• Who should care for my minor children?
• Are there family members who may need extra support?
• Do I have a blended family or previous relationship to consider?
• Do I own a business, rental property, or assets outside Alberta?
• Are there personal values or charitable causes I want reflected in my plan?
This does not need to be a dramatic conversation. You can start with a simple family discussion over coffee.
For example, a young Edmonton family with a mortgage may want to focus on income replacement, mortgage protection, and guardianship for their children. A retired couple may be more concerned with simplifying their estate, protecting a surviving spouse, and distributing assets fairly among adult children.
There is no one-size-fits-all answer.
Your estate plan should reflect your family, your responsibilities, your values, and your financial situation.
A simple starting exercise
Write down three things:
1. Who you want to protect
2. What you want to preserve
3. What you want to avoid
You may want to protect your children, preserve your home, and avoid confusion or conflict between family members.
That is enough to begin.
Step 2: Create a Complete List of Your Assets and Debts
Many families have more financial accounts than they realize. An estate plan cannot work smoothly if nobody knows what exists.
Create a basic inventory of what you own and what you owe. Include:
• Chequing and savings accounts
• TFSAs, RRSPs, RRIFs, and other registered plans
• Non-registered investment accounts
• Your home or other real estate
• Vehicles, recreational property, or valuable personal items
• Business interests or partnership agreements
• Life insurance policies
• Pension benefits
• Mortgages, loans, lines of credit, and credit cards
• Digital assets and important online accounts
You do not need to calculate every item perfectly on the first attempt. A rough list is far better than relying on memory during a stressful time.
For each asset, record:
• The institution or company
• The account or policy type
• The approximate value
• The account number or policy number
• The named beneficiary, if applicable
• Where the documents are stored
Keep this information secure. You do not need to write down every password in an unsecured document. Instead, make sure your executor or trusted decision-maker knows how to access your records safely.
An organized estate is easier for your family to administer.
It can also reveal gaps. Perhaps an old investment account still lists a former spouse. Perhaps you have a life insurance policy but cannot find the policy documents. Perhaps your family is not aware of a small workplace pension.
This is why estate planning and wealth management in Alberta are closely connected. Your investments, insurance, retirement savings, debts, and estate documents should work together rather than sit in separate folders.
Step 3: Review Your Will, Power of Attorney, and Personal Directive
If you already have these documents, locate them and check whether they still reflect your life today.
If you do not have them, this year may be the right time to speak with an Alberta lawyer about preparing them.
Your circumstances may have changed since you last reviewed your documents:
• You got married or divorced.
• You welcomed a child.
• Your children became adults.
• A named executor moved away or became unable to serve.
• A beneficiary died.
• You purchased a home.
• You started or sold a business.
• Your financial situation changed significantly.
• Your family structure changed.
A will can name an executor, sometimes called a personal representative, to administer your estate. It may also name a guardian for minor children. Your personal directive and enduring power of attorney address different decisions while you are alive.
The documents should be coordinated, but they are not interchangeable.
A will cannot replace a personal directive. A personal directive cannot replace an enduring power of attorney.
JK Asset Management can help you identify the financial information and planning questions to discuss. When customized legal documents or specialized estate advice are required, we can help connect you with appropriate professionals through our referral services.
You do not need to understand every legal detail before starting. Bring your questions. A qualified professional can explain what applies to your circumstances.
Step 4: Coordinate Life Insurance and Beneficiary Designations
A will is important, but it may not control every asset you own.
Life insurance policies and many registered accounts allow you to name beneficiaries directly. These designations can determine who receives the proceeds, often outside the estate process. That means an outdated beneficiary form may create a result you did not intend.
Review the beneficiaries listed on:
• Life insurance policies
• TFSAs
• RRSPs
• RRIFs
• Workplace pension plans
• Other accounts that allow direct beneficiary designations
Then compare those designations with your will and overall wishes.
For example, imagine your will leaves everything equally to your two children, but an old life insurance policy still names only one child. The policy designation may create an imbalance or confusion for your family.
This is not about assuming something went wrong. It is about checking.
Life insurance may also support an estate plan by helping with:
• Income replacement
• Mortgage and debt protection
• Final expenses
• Providing liquidity for the estate
• Supporting a spouse or dependent
• Equalizing inheritances
• Leaving a legacy
Term life insurance may be appropriate for temporary needs such as raising children or paying a mortgage. Permanent life insurance may be appropriate for lifelong protection, legacy planning, or certain estate objectives. The right solution depends on your needs, budget, health, time horizon, and broader financial plan.
Review your options through JK Asset Management’s insurance services, where recommendations are designed around your circumstances rather than a standard formula.
Your insurance plan should support your estate plan: not contradict it.
Step 5: Share the Plan and Schedule an Annual Review
An estate plan is not finished when the documents are signed.
Your executor and trusted decision-makers should know:
• That the documents exist
• Where the original documents are stored
• How to contact your financial advisor
• Which lawyer prepared the documents
• Where your asset inventory is located
• Which insurance policies and accounts you have
• How to access important information when needed
You do not have to share every private financial detail. But complete secrecy can create unnecessary stress for the people who may eventually need to help.
Choose a secure location and tell the right people how to find it.
Then set a reminder to review your plan at least once a year and after major life changes.
A yearly review may include:
• Updating beneficiaries
• Reviewing insurance coverage
• Checking account ownership
• Updating your asset inventory
• Confirming your executor and decision-makers
• Reviewing retirement and investment strategies
• Speaking with your lawyer about changes to your legal documents
At JK Asset Management, we believe financial planning is an ongoing partnership. Your estate plan should evolve as your family, career, income, investments, insurance needs, and retirement objectives change. Our financial planning services can help bring these pieces together.
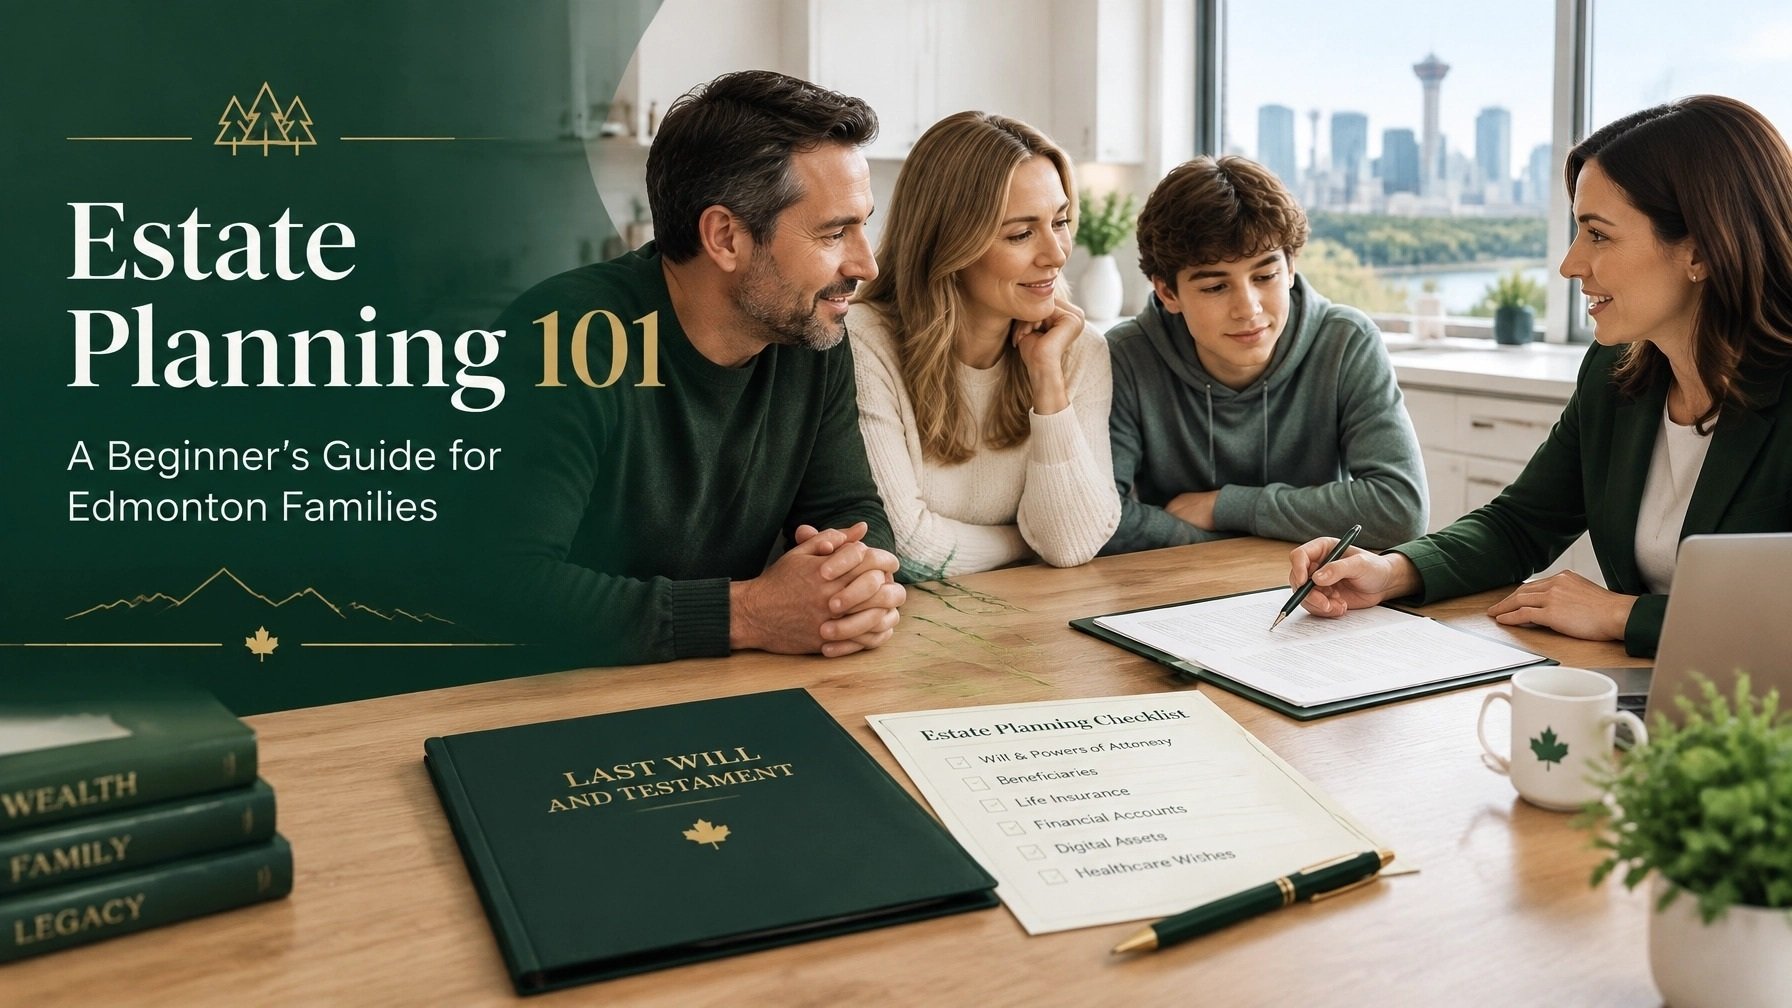
A Practical Estate Planning Checklist for This Year
Start where you are. You do not need a perfect plan on day one.
• Write down your family’s main priorities.
• List your assets, debts, insurance, and important accounts.
• Locate your will, enduring power of attorney, and personal directive.
• Review your executor and decision-makers.
• Check beneficiaries on life insurance and registered accounts.
• Review whether your insurance still matches your family’s needs.
• Organize important documents securely.
• Tell trusted people where the information can be found.
• Schedule a professional review.
• Set an annual reminder to revisit the plan.
Five minutes of organization today can save your family hours of uncertainty later.
Start Your Estate Plan With a Conversation
Estate planning in Edmonton does not have to be intimidating, expensive, or reserved for another stage of life.
You can start with a list. You can start with questions. You can start by admitting that you are unsure who your current beneficiaries are.
That is completely okay.
At JK Asset Management, we take time to understand your goals, family situation, assets, insurance coverage, and concerns. We can help you organize the financial side of your plan, coordinate estate planning with your broader wealth management strategy, and connect you with appropriate legal or specialized professionals when needed.
There is no requirement to have substantial savings. There is no need to arrive with a perfect spreadsheet. There is no obligation to make a decision before you understand your options.
Book a consultation with JK Asset Management and take one practical step toward protecting your family’s future.
Website: https://www.jkassetmanagement.ca/index
Phone: (780) 399-5471
Email: kapler@jkassetmanagement.ca
Contact Us: https://www.jkassetmanagement.ca/contact
No Family Left Behind.
This article is provided for general educational purposes and is not legal, tax, or investment advice. Estate planning laws and tax considerations depend on your circumstances. Speak with a qualified Alberta lawyer or tax professional for advice about your legal documents and situation. Insurance and investment recommendations should be reviewed with a licensed professional based on your needs, objectives, risk tolerance, and financial position.