About one in three Canadians are navigating a major life change without life insurance.
That may mean getting married, buying a home, welcoming a baby, changing jobs, becoming self-employed, or going through a separation without coverage in place.
A 2026 TD Insurance survey found that roughly 32% of Canadian adults said they have no life insurance at all. The same survey identified perceived cost and reliance on workplace coverage as common reasons people delay reviewing their protection.
This is not usually a deliberate decision.
Most people do not wake up and decide, “I want to remain uninsured for the next five years.” They mean to look into it next month. Then the mortgage closes, the baby arrives, work becomes busy, or another bill takes priority.
Next month becomes next year.
If you are in that position, you are not alone and not behind. The important thing is to recognize the gap and take one manageable step.
Why Major Life Events Should Trigger a Coverage Review
Life insurance is often set at one moment.
Your life does not stay at that moment.
Your income may change. Your household may grow. Your debts may increase. Your workplace benefits may disappear. Your responsibilities may look completely different from the day you first applied for coverage.
Here are the life events that deserve a review.
Buying a Home
A mortgage can become one of your family’s largest financial obligations. If one income disappears, the surviving household may need to keep making mortgage payments while also managing childcare, utilities, groceries, and other expenses.
Your coverage may need to reflect the mortgage, not just your income.
Having a Child
A new child changes both your financial responsibilities and the cost of replacing your time. If something happens to one parent, the surviving parent may need additional childcare, household help, transportation support, or time away from work.
Life insurance may help create breathing room during that transition.
Getting Married or Entering a Common-Law Relationship
A partner may depend on your income, benefits, pension contributions or unpaid household work. Combining households is a useful time to discuss what would happen if one person were no longer able to contribute.
Changing Jobs
Workplace coverage usually does not automatically follow you to a new employer. A job change may create a temporary gap, reduce your benefits, or introduce different limits and exclusions.
Do not assume that “benefits” at the new job means your previous level of protection is still in place.
Getting Divorced or Separating
Beneficiaries, ownership arrangements and financial responsibilities may change after a separation.
You may also become responsible for support payments, a mortgage or children’s expenses on a different household budget.
This is a time to review, not simply cancel, your coverage.
Starting a Business or Becoming Self-Employed
Self-employed Albertans, contractors, tradespeople and oil and gas workers may not have employer-paid life or disability benefits. Income may also fluctuate, making it harder to know how much protection is appropriate.
Survey reporting suggests that only about a quarter of self-employed Canadians hold disability coverage, leaving many people exposed if illness or injury interrupts their ability to earn.
Taking on a Larger Mortgage
A larger home, refinancing, or a new line of credit can increase the amount your family would need to manage if your income were lost.
Becoming the Primary Earner
If your income becomes the main source of household support, your insurance needs may change even if your family size does not.
Caring for a Parent or Dependent
A dependent adult, aging parent, or family member with long-term support needs may require care for many years. That responsibility can create financial needs that were not part of your original plan.
The takeaway: Review coverage when your responsibilities change, not only when you remember the policy exists.
Why Workplace Coverage Leaves So Many Families Uninsured
Workplace life insurance can be valuable. It is often an important part of a family’s financial plan.
But it is also one of the most common sources of confusion.
Group life insurance is typically based on a small multiple of your salary, often one or two times your annual income, although the exact amount depends on your employer’s plan. For a household with a mortgage, children and several years of lost income to replace, that amount may not be enough.
The 2026 TD Insurance survey found that 44% of Canadians with workplace life insurance either do not know how much coverage they have or are unsure whether it is enough. It also found that 34% had delayed purchasing or reviewing life insurance because they assumed workplace coverage was sufficient.
This is the single most common misconception:
| Having workplace coverage does not necessarily mean having enough coverage. |
There is another practical issue. Group coverage usually ends, changes, or becomes less affordable when you:
• Leave your job
• Are laid off
• Retire
• Move to a different employer
• Lose eligibility under the group plan
It is easy to leave a job and lose coverage without noticing. It is also possible to reduce protection after
retirement or a layoff without fully considering the effect on your partner or dependants.
Check your benefits booklet. Find the amount. Ask what happens when employment ends.
That five-minute review may reveal more than you expect.
“Life Insurance Is Too Expensive.” Let’s Talk Honestly
Cost is a real concern. Families are managing groceries, mortgages, childcare, debt payments and changing interest rates. It is reasonable to ask whether insurance fits the budget.
The helpful distinction is between perceived cost and the cost of a personal quote.
Term life insurance in Canada is generally less expensive than many people assume, especially when compared with the financial responsibilities it may protect. However, there is no universal premium.
Cost depends on factors such as:
• Your age
• Your health
• The coverage amount
• The length of the policy term
• Your sex
• Smoking and other underwriting factors
• The type of insurance selected
A personal quote is needed to understand your actual options. It would be misleading to promise a general price or suggest that one amount applies to every family.
Many people overestimate the cost by several times because they have never received a quote. Others wait because they expect their income to improve later.
Waiting can be the expensive choice.
Premiums generally rise as you get older. A health change may also make coverage more difficult, or, in some cases, impossible to obtain on the same terms.
That does not mean you should rush into a policy. It means a review can give you information before you make a decision.
No pressure. Just clarity.
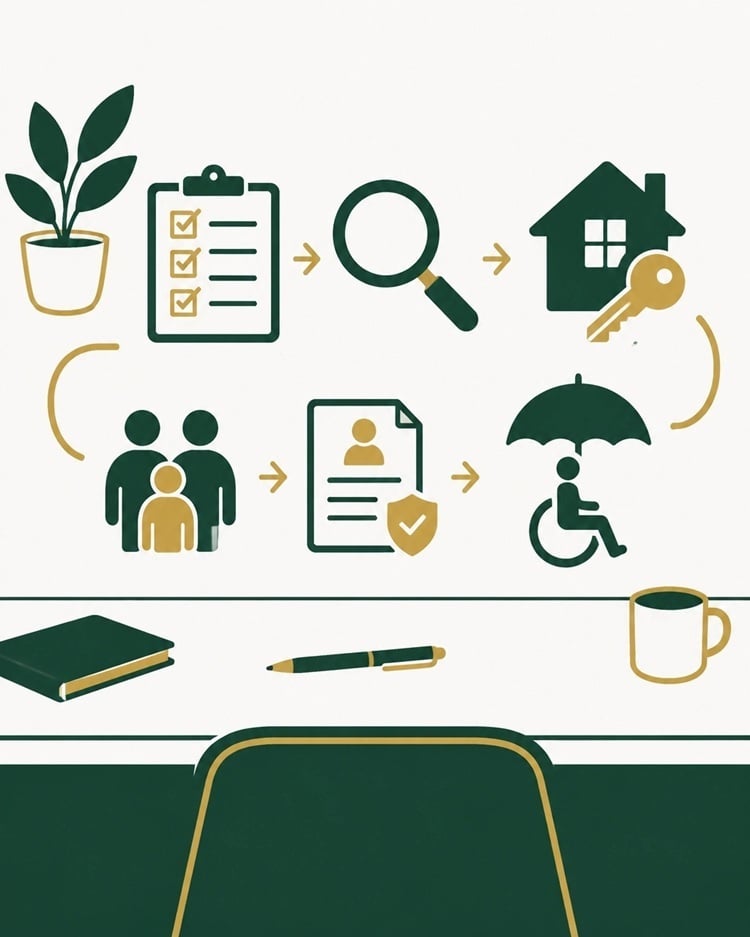
What Should You Actually Review?
You do not need to understand every insurance term before beginning. Start with the basics.
1. Does coverage exist at all?
Check personal policies, workplace benefits, mortgage-related coverage and any older policies you
may have forgotten.
Then ask whether the coverage follows you if you change jobs.
2. Is the amount still appropriate?
Consider your current:
• Mortgage and other debts
• Income
• Number and age of dependants
• Childcare and education goals
• Savings and investments
• Expected survivor benefits
• Household expenses
A 14.5% national coverage gap was reported in separate 2026 Canadian insurance survey research, meaning many insured households still carry less coverage than their circumstances may require.
That figure is a survey finding, not a judgment about your family. It is simply a reminder that having insurance and having enough insurance are different questions.
3. Are your beneficiaries current?
Marriage, separation, divorce, new children, and family changes can affect beneficiary choices. Review the names and designations on your policy and understand how they interact with your broader estate arrangements.
4. Are both partners considered?
The stay-at-home parent may not receive a paycheque, but their work still has replacement cost.
Childcare, meal preparation, transportation, household management and daily care all take time and
money. A coverage review should consider both partners, not only the person with the higher income.
5. Do you have disability or accident and sickness protection?
For a working-age adult, the risk of being unable to work because of illness or injury is generally more likely than dying during those working years. Life insurance protects against the loss of a person. Disability coverage may help protect the income that person is still alive to earn.
These are different risks.
Your review may include workplace disability benefits, government programs, and accident and sickness coverage, along with any gaps that could affect your mortgage and household budget.
Why the Gap Matters More Than People Think
Life insurance is not only about paying a death benefit.
It is about protecting choices.
Without enough coverage, a surviving spouse may need to sell or refinance a mortgage quickly. They
may return to work sooner than planned, increase work hours or reduce time spent caring for children.
A child’s education savings plan may be interrupted. Debt may need to be managed during a period
of grief. A family may have to make permanent financial decisions before they have had time to adjust.
These outcomes are not guaranteed. They are simply possibilities worth considering when reviewing
your responsibilities.
The goal is not to create fear.
The goal is to give your family more time, more flexibility and more control if life changes suddenly.
A Simple Starting Point: Five Minutes and One Question
You do not need perfect finances before getting insured.
You do not need substantial savings. You do not need to know the exact amount of coverage you need. You do not need to choose a product or insurer today.
Start here:
1. Find your workplace benefits booklet.
2. Look for the life insurance amount.
3. Check whether the coverage ends when employment ends.
4. Write down your mortgage, debts and dependants.
5. Note whether both partners have protection.
6. Identify one question you want answered.
That is enough for a first conversation.
At JK Asset Management, our approach is to review insurance alongside your broader financial planning in Edmonton needs, including income, debt, investments, retirement objectives and estate considerations. We explain options in plain language and help you understand what may be appropriate for your circumstances.
You can also read our related guide on life insurance for Edmonton families with a mortgage or learn more about our insurance solutions.
There is no shame in having delayed the decision. The survey findings show how common it is. Start where you are. Ask one question. Take one step.
Contact JK Asset Management
• Website: https://www.jkassetmanagement.ca/index
• Phone: (780) 399-5471
• Email: kapler@jkassetmanagement.ca
• Contact page: https://www.jkassetmanagement.ca/contact
No Family Left Behind.
This article is for general educational purposes only and is not insurance, investment, tax or legal advice. The percentages and coverage-gap figures referenced above are survey findings and do not predict the circumstances of any individual or family. Coverage availability, premiums, policy terms, exclusions, underwriting decisions, and beneficiary rules vary according to personal circumstances and insurer requirements. A qualified professional should review your needs before you purchase, replace or change insurance coverage.